Published
High-Net-Worth Income and Spending: 2024 Benchmark Report
High-Net-Worth Income and Spending: 2024 Benchmark Report
Explore the latest investment trends and strategies for high-net-worth individuals, guided by Long Angle's 2024 high-net-worth asset allocation study.
Benchmark Study
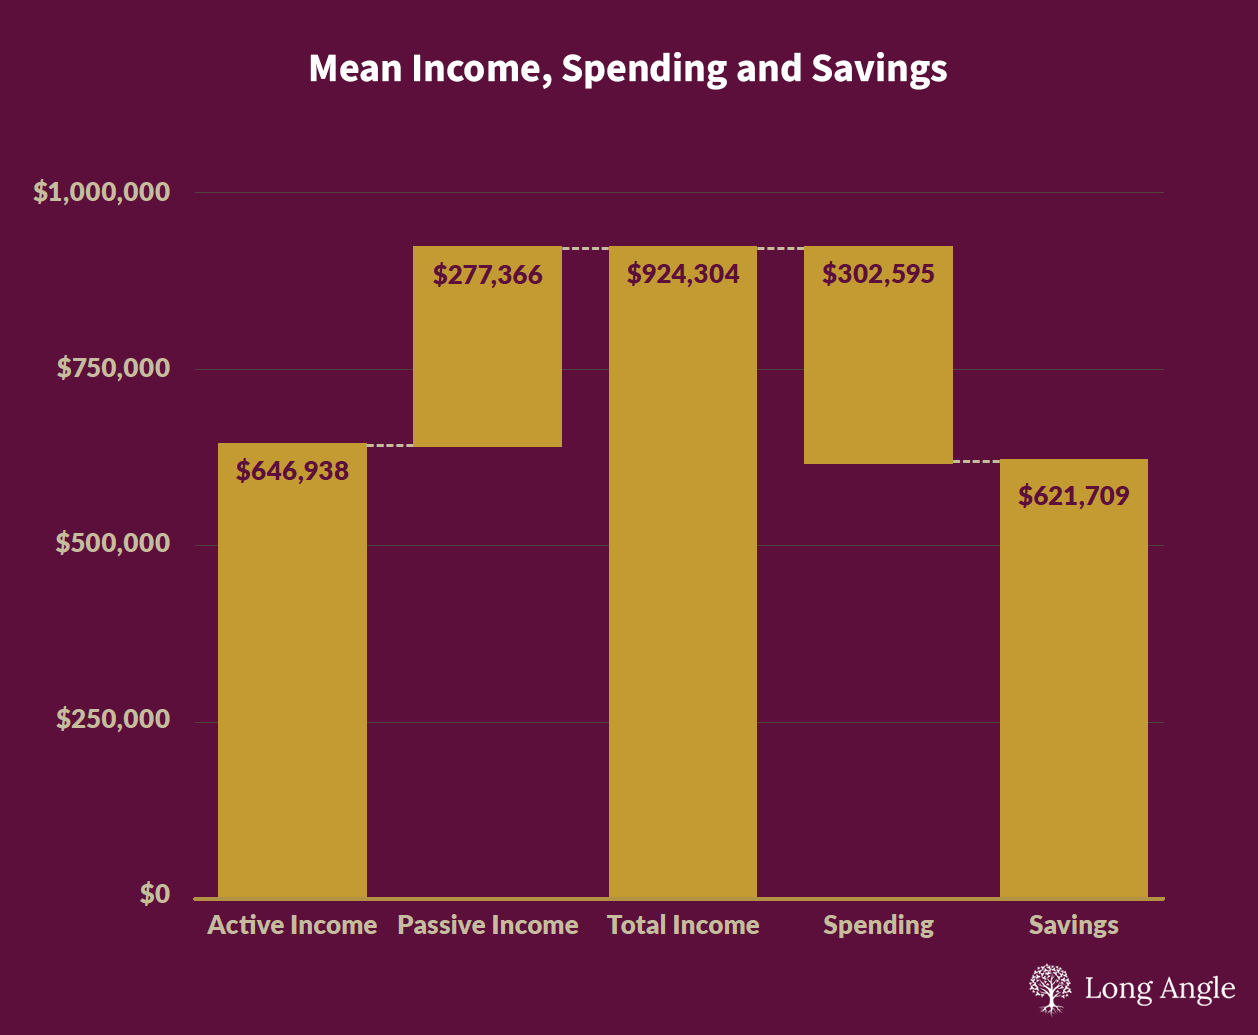
On average, Long Angle members save nearly two-thirds of their after-tax income, banking $621,709 a year on $924,304 in total earnings, while high earners save an even larger share: those making over $1 million after tax realize more than 80% of it as free cash flow. Passive income becomes the dominant source only above $25 million in net worth, where it covers 70% of total income, compared to 6% for top earners under that threshold. Findings come from Long Angle's 2024 High-Net-Worth Income and Spending Report, the community's inaugural study on this topic, published September 2024.
Key Takeaways
- Respondents save nearly two-thirds of after-tax income on average, translating to $621,709 a year on $924,304 in total income, though median figures run lower at $325,583 saved on $625,822 earned.
- Passive income share flips sharply with net worth: those above $25 million draw 70% of income from passive sources, versus just 6% for those earning over $1 million annually. These are two different segmentation bases and shouldn't be read as one continuous trend.
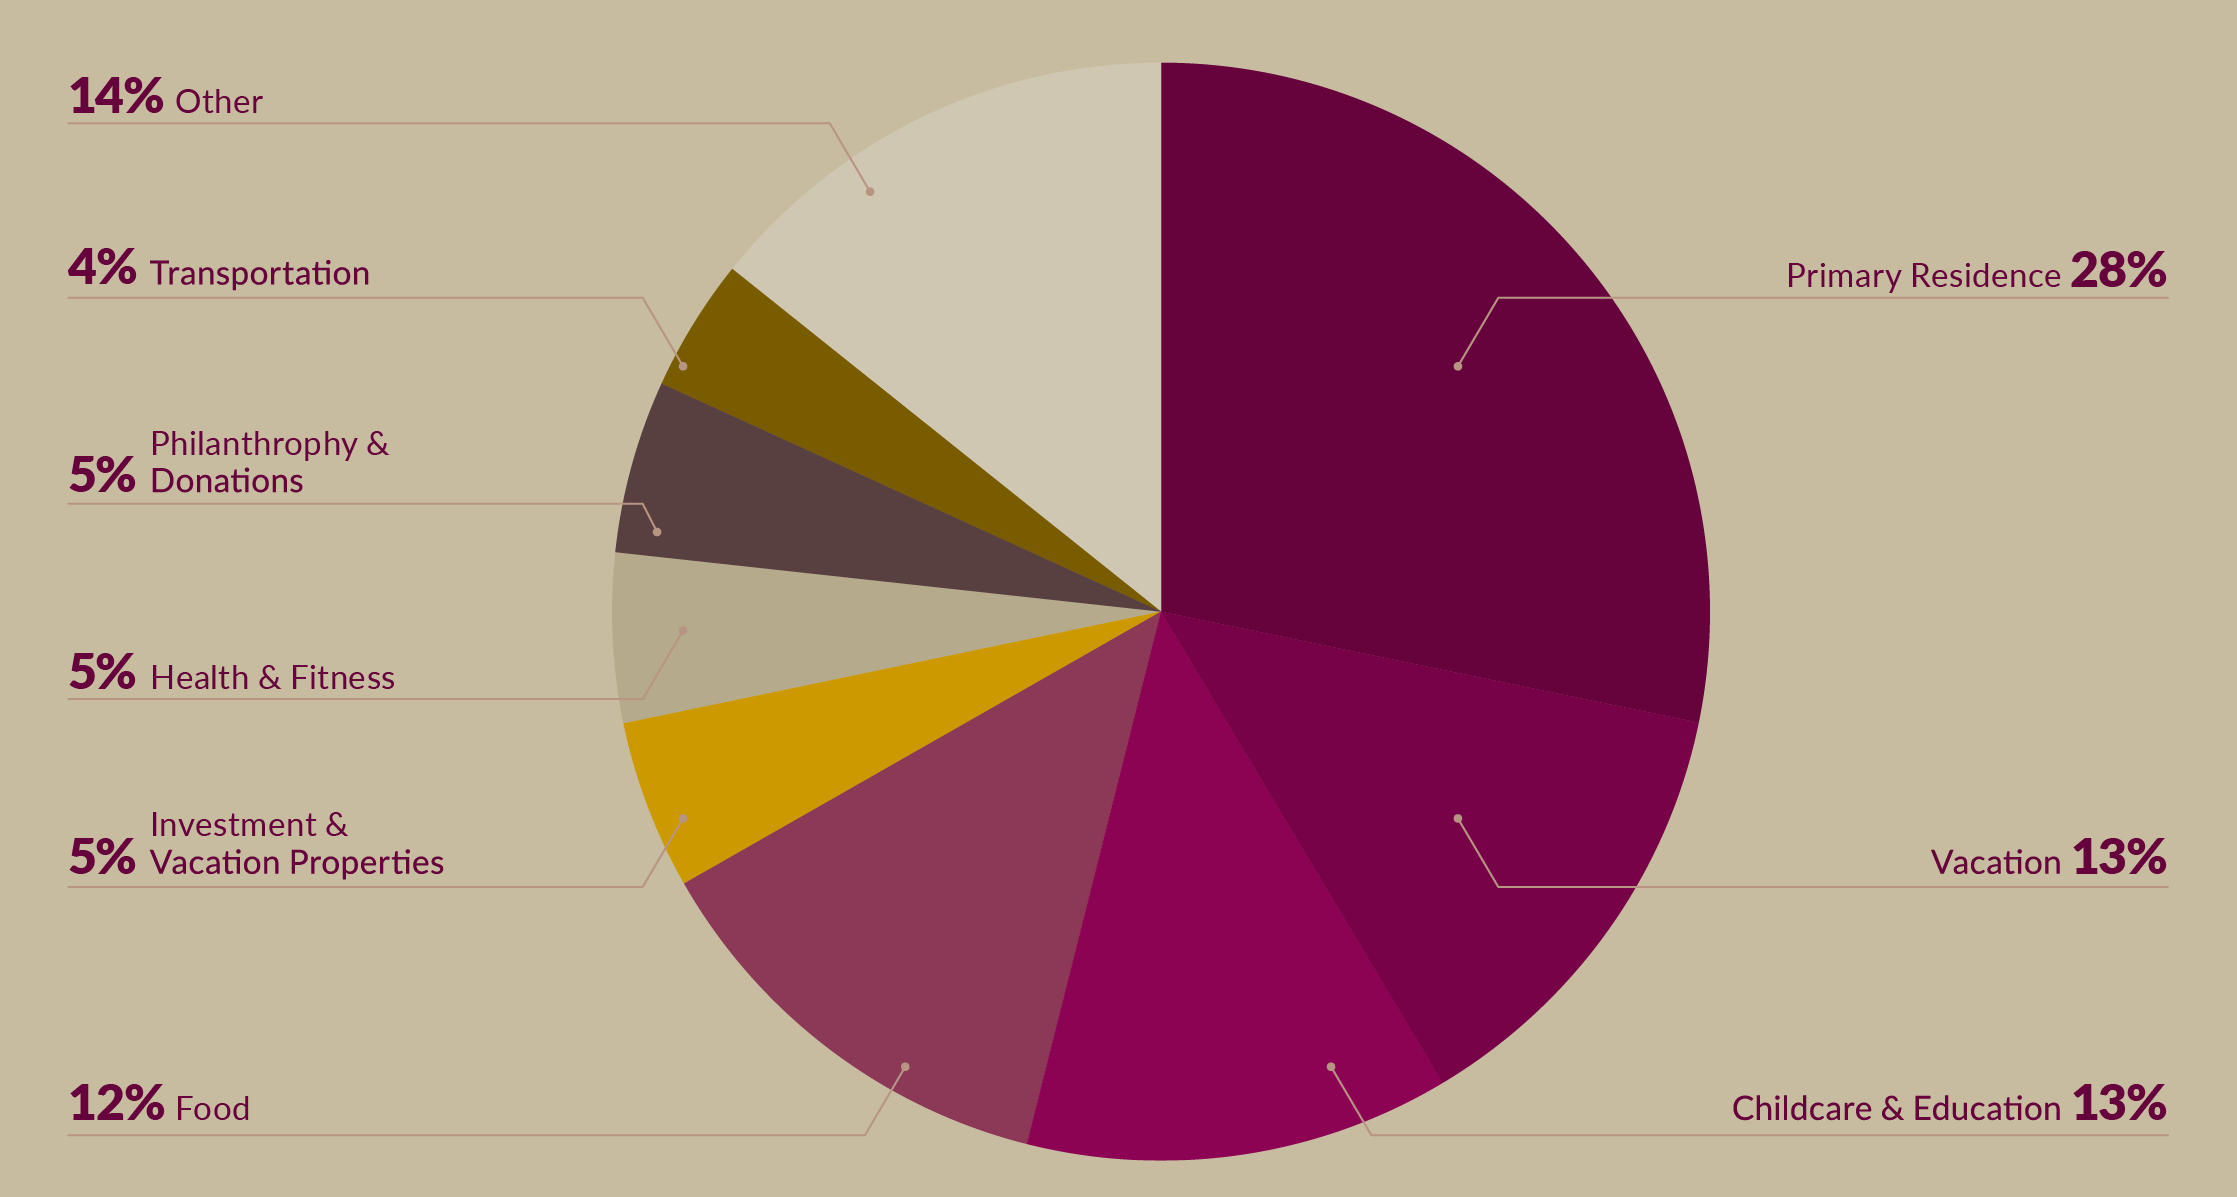
- Housing is the largest single expense at 28% of spending, followed by childcare/education and vacation tied at 13% each.
- Budgeting habits are inconsistent even at this wealth level: 46% only track expenses without a formal plan, 28% both budget and track, and 26% do neither.
- The report gives no stated respondent count and uses median figures throughout except where marked otherwise, a methodology gap that limits how confidently these findings should be read.
Insights from Long Angle’s 2024 High-Net-Worth Spending Study
This data represents the yearly spending habits of the Long Angle high-net-worth community based on 2024 data. The goal was to gather unbiased information to paint an accurate picture of the financial habits of the high-net-worth individuals and households.
High-Net-Worth Income
On average, Long Angle members earn $924,000 in pre-tax income annually. Most members fall into the post-tax income range of $250,000 to $1 million per year. Approximately two-thirds of this income is saved, translating to $621,000 each year.
Most respondents (78%) are actively earning, while the remaining 22% are retired, predominantly early retirees.
Active vs. Passive Income for High-Net-Worth Individuals
High-net-worth individuals often have highly diversified portfolios, earning income from various sources:
- Active income sources (i.e. salaries and private business earnings) constitute 68% of total income.
- Passive income sources (i.e. brokerage dividends and 401(k)/IRA dividends) account for 32% of total income.
As net worth increases, members can rely more on passive income. Those with net worths over $25 million receive 70% of their income from passive sources, compared to only 6% for individuals earning over $1 million a year.
High-Net-Worth Financial Planning Strategies
The top financial goal for high-net-worth individuals is achieving financial independence, where passive income is sufficient to support their lifestyle. Reaching this goal typically requires a net worth of $25 million or more; most members at this level earn more in annual passive income than they spend.
High-net-worth budgeting can be complex due to the large amount of available money and the vast potential for how to spend it. As such, there are different preferences in terms of the amount of oversight high-net-worth individuals desire over their expenses and budget.
- Close to half of respondents only track their expenses.
- 28% track expenses and also maintain a budgeting plan.
- A quarter of respondents do not use any formal budgeting or tracking system.
As one would expect, high-net-worth individuals generally employ aggressive savings strategies to build up their portfolios. In fact, those with post-tax incomes exceeding $1 million save more than 80% of their income as net free cash flow.
High-Net-Worth Spending Habits
Analyzing how the wealthy spend their money shows what expense categories are most important when supporting a high-net-worth lifestyle.
Significant expense categories include:
- Housing: About 28% of total spending goes toward primary residences.
- For those who rent (under 20% of members), annual rental expenses average $45,213.
- For homeowners, annual mortgage and property taxes average just under $50,000.
- Childcare and Education: About 13% of total spending supports children and dependents, including childcare, education, and other expenses such as healthcare.
- Vacations: High-net-worth individuals generally spend an average of $12,254 per year on vacations, with most of that money spent on hotels and resorts. Vacation spending increases with net-worth and income.
- Food: Food-related expenses account for 12% of total spending. Most of that is spent on groceries, with restaurant costs taking up just slightly less.
Other categories, which account for a smaller portion of high-net-worth spending, include investment and vacation properties, health and fitness, philanthropy, and transportation.
These high-net-worth spending habits reflect a willingness to spend more on standard expenses that support overall quality of life. While most consumers spend a large portion of their income on expenses such as housing and food, high-net-worth individuals are able to invest in higher quality purchases in those categories. Vacations represent the biggest recreational expense.
Asset Allocation by Net Worth
- Under $5 Million – 62% allocated to public equities, with lower exposure to alternatives and private markets.
- $5 Million to $25 Million – Greater allocation to private equity and venture capital. Real estate remains a key investment.
- Above $25 Million – 38% of portfolios allocated to private businesses, reflecting increased access to direct investments.
The study highlights a progression from growth-oriented strategies among younger investors to a focus on wealth preservation in older age and higher net worth brackets. This nuanced approach underscores the importance of aligning asset allocation with one's investment horizon, risk tolerance, and financial objectives, serving as a guide for both investors and advisors in optimizing portfolio strategies.
For a detailed breakdown of asset allocation trends, investment strategies, and risk preferences among high-net-worth individuals, download the full 2025 High-Net-Worth Asset Allocation Study by Long Angle.
About Long Angle
Long Angle is a private community of high-net-worth investors who leverage their collective expertise and scale to access and underwrite some of the world's best alternative asset investments. Asset classes range from private equity, search funds, and private credit to secondaries, real estate, and venture capital.
Long Angle is a high-net-worth peer community, not a wealth manager. Members independently make their investment decisions on a deal-by-deal basis. They are treated as partners in every investment, with full transparency regarding the investment team's diligence and underwriting processes. All members receive equal access to negotiated fee discounts.
Membership is free but requires an interview with a current community member, as well as validation of investable assets. Apply Now »
Frequently Asked Questions
What is considered high net worth?
A high-net-worth individual is generally considered someone with a net worth of at least $1 million. In the Long Angle community, most members have portfolios worth $5 to $50 million.
What do high-net-worth individuals invest in?
High-net-worth investors have plenty of opportunities to consider, both traditional and alternative. Alternative investments allow HNWIs to tap into asset classes from private equity to real estate to secondaries. These unique opportunities help with portfolio diversification and often offer greater return potential.
Net worth vs. income: what’s the difference for HNWI?
Net worth measures total assets (minus liabilities) and represents a HNWI’s overall wealth. Income is how much an individual earns for a year. While people with high incomes often have high net worths, that is not always the case.
Individuals with high net worths are generally able to rely more on passive income. In contrast, the amount of income coming from passive sources tends to decrease as income increases.
What is a safe withdrawal rate?
The standard recommended safe withdrawal rate is 3% to 4%. This ensures that only sustainable amounts of money come out of a portfolio, paving the way for successful high-net-worth retirement planning and making it easier to achieve financial goals.
This report found that nearly half of respondents feel comfortable withdrawing from their portfolios using a safe withdrawal rate.
How should high-net-worth individuals plan their finances?
Financial planning for high-net-worth individuals is complex due to the sheer volume of assets. There are many facets to consider, including wealth management, high-net-worth tax planning, estate planning, retirement planning, risk management, and portfolio diversification.
Many high-net-worth individuals choose to work with financial advisers who can help them allocate assets wisely. In addition, or for those who choose to manage their finances themselves, it can be invaluable to network with high-net-worth peers who can share insights and ideas.
Research