Written by Scott Nixon
How Much Does PPLI Cost? Every Charge, One-Time and Recurring
How Much Does PPLI Cost? Every Charge, One-Time and Recurring
One-time charges, policy-level insurance costs and fund fees are three different things. What drives each, and when the structure is not worth paying for.
Scott Nixon
Private placement life insurance costs split into one-time charges paid as the policy is funded and recurring charges paid every year it stays in force. The one-time side covers a federal deferred acquisition cost pass-through of roughly 1 percent of premium, state premium tax set by the policy's domicile, and a carrier issue charge. The recurring side divides again, into policy-level insurance charges and the ordinary management fees on whatever is held inside. The Wall Street Journal reported in August 2026 that PPLI typically runs 2 to 4 percent annually, with a practical floor near $5 million of premium.
Key Takeaways
- PPLI costs divide three ways: one-time charges on premium, policy-level insurance charges, and the ordinary fund fees you would pay holding the same assets anywhere.
- Published figures like 2 to 4 percent blend all three, which is why they are difficult to compare against anything.
- State premium tax is set by the policy's domicile rather than your residence, and the spread between domiciles is wider than most negotiated differences.
- The cost of insurance usually falls over time. The rate rises with age, but the death benefit the policy must carry falls, and the charge is calculated on the gap.
- The $5 million figure is a market convention driven by fixed costs, not a rule in the tax code.
- If you hold only index funds, need the money inside five years, or want to pick the investments, the costs buy you very little.
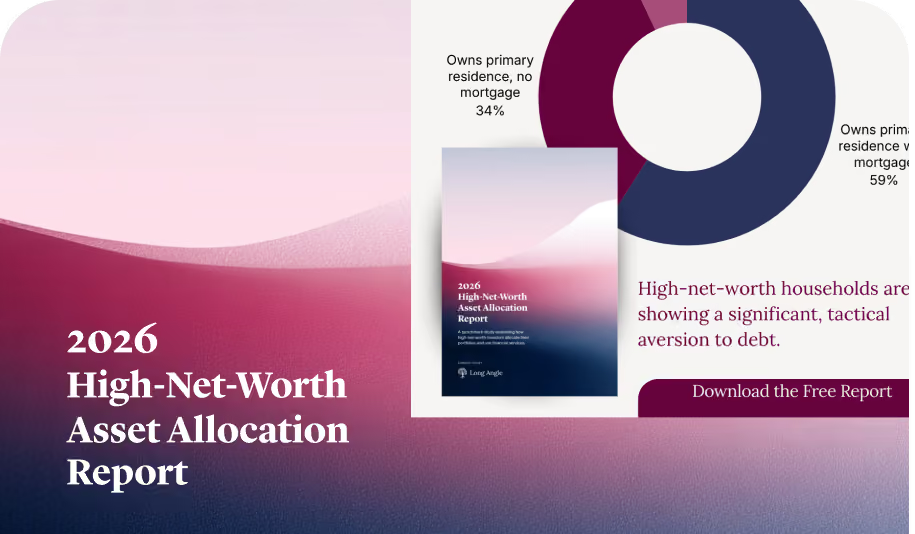
2026 High-Net-Worth Asset Allocation Report
See how high-net-worth investors with an average net worth of $17M are allocating across public equities, private markets, real estate, bonds and cash. Based on benchmark data from 230+ respondents.
What You Pay Once, Before the Policy Earns Anything
A PPLI policy carries several one-time charges at funding: a federal deferred acquisition cost pass-through, state premium tax, a carrier issue charge, and often the cost of forming an owning entity.
The federal charge is the one most readers have never heard of. Section 848 of the tax code requires an insurer to capitalize a portion of the premiums it receives and recover that amount over a period of years rather than deducting it immediately. In a retail policy the cost is buried in the product's pricing. In a private placement policy it is passed through, which is why it shows up as a visible line at funding.
State premium tax is levied by the state where the policy is domiciled. The carrier issue charge covers putting the policy in force, and it scales with how much underwriting the case required rather than with the premium itself.
| One-time charge | What it is | What drives the size |
|---|---|---|
| Federal deferred acquisition cost (DAC) | Carriers must capitalize a share of premium received and recover it over time. On a private placement policy it is passed through at funding rather than absorbed into retail pricing. | A percentage of premium paid. Roughly 1%. |
| State premium tax | A tax the policy's state of domicile levies on premium received. | The domicile, not your residence. The spread between domiciles is wide. |
| Carrier issue charge | A one-time charge for issuing the policy. | The depth of underwriting required. Typically low four figures. |
| Owning entity formation | Optional. An LLC used to set the policy's domicile. | Formation cost plus an annual maintenance cost while it stays in place. |
Source: Internal Revenue Code sections 848 and 7702, and state premium tax statutes. Category ranges, not a quote for any policy. Charges vary by carrier, age, health and domicile.
The distinction that matters: every charge above is calculated on premium, not on assets, and each is paid once. A reader comparing a PPLI policy to a fund's expense ratio is comparing two different units. A one-time charge on contributed capital becomes a smaller annual drag every year the policy stays in force, which is why holding period changes the answer more than any single line item.
What You Pay Every Year, and Which Parts Are Negotiable
Recurring PPLI costs sit in two separate layers: insurance charges at the policy level, and investment management fees at the fund level. Only the first layer exists because of the policy.
At the policy level there are two components. Mortality and expense charges are the commercial terms the carrier and the broker charge for running the contract, and they are negotiated. The cost of insurance is different: it is an actuarial charge for the death benefit sitting above the cash value, priced on age and health, and it is not a negotiable commercial term.
At the fund level sit the management fee and the administrative costs of whatever is held inside the policy. These are the ordinary costs of owning private credit, hedge funds or any other strategy. They are charged whether the assets sit inside an insurance contract or in a taxable brokerage account.
Most published cost figures blend the two layers, which is what makes a range like 2 to 4 percent unreadable. The honest question is not what the policy costs. It is what the policy costs on top of what you were going to pay anyway. Separating the layers is also how you compare it against ordinary wealth management fees, which are quoted on the same blended basis.
Why Your Domicile Changes the Bill More Than Your Carrier Does
State premium tax is charged by the policy's state of domicile, and the gap between the cheapest domiciles and the common ones is wider than most negotiated cost differences.
Alaska and South Dakota tax premium on a graduated basis that applies the meaningful rate only to an initial slice of each year's premium. Most states apply a flat rate of roughly 2 percent to the whole premium. On a large policy funded over several years, that structural difference compounds into a materially different one-time bill.
| Policy domicile | How premium tax is applied | Effect on a large premium |
|---|---|---|
| Alaska | A higher rate on the first slice of each year's premium, then a very low rate above it. | The effective rate falls sharply as the premium grows. |
| South Dakota | A comparable graduated structure. The other common PPLI domicile. | Same effect. |
| Most other states | A flat rate, commonly around 2%, applied to the entire premium. | The effective rate does not fall with size. |
Source: State insurance premium tax statutes. Structural comparison. Confirm current statutory rates for a specific domicile before relying on them.
This is the reason PPLI policies are so often owned through a limited liability company formed in a state the policyholder does not live in. The policy's domicile follows the owner entity, not the insured, so residence is irrelevant. The entity carries its own formation and annual costs, and those need to be netted against the premium tax it saves. On a policy near the bottom of the size range the entity can cost more than it saves.
There is a second reason the structure appears, and it is about time rather than money. Some domiciles permit a longer backdating window, which lets a policyholder compress the multi-year funding period the tax rules require. Getting capital into a tax-deferred position sooner has a value that does not appear on any fee schedule.
Why the Cost of Insurance Falls as You Get Older
The cost of insurance rate rises every year with age, and the amount of insurance the policy is required to carry falls, so the dollar charge usually declines rather than climbing.
The mechanism sits in two rules. Section 7702 requires a life insurance contract to keep its death benefit above its cash value by a defined margin, known as the corridor. Section 7702A separately limits how quickly a policy can be funded before it is reclassified as a modified endowment contract and loses part of its tax treatment.
A PPLI policy is deliberately sized to the smallest death benefit that stays outside modified endowment treatment, because the cost of insurance is charged on the death benefit above cash value. As the investments grow, the cash value rises toward the death benefit, the amount genuinely at risk shrinks, and the charge calculated on it shrinks with it.
That inverts the usual logic. In most life insurance, more death benefit is the point of the purchase. Here it is the cost. The structure is built to carry the least insurance the rules will accept.
It also explains why age alone is a weaker disqualifier than readers assume. An older policyholder faces a higher rate, and also a lower required death benefit, because the corridor requirement falls with age. A rising rate applied to a shrinking base does not produce the cost curve most people expect.
Why $5 Million Is a Market Convention, Not a Rule
The $5 million figure widely quoted as a PPLI minimum is a market convention produced by economics, not a legal threshold in the tax code.
The Wall Street Journal reported in August 2026 that advisers put private placement life insurance fees as high as 2 to 4 percent a year in a policy's early years, and that a policyholder generally needs to fund at least $5 million of premium for the tax savings to outweigh the cost and complexity. Both figures describe how the market has priced itself rather than what the structure requires.
The reason is fixed cost. A carrier issue charge, an entity, an audit and an administrator cost close to the same whether the policy holds $2 million or $20 million, so they are a far larger proportional drag on a small policy. The negotiation is fixed cost too: agreeing commercial terms takes the same hours at any size, which is why counterparties set a floor below which it is not worth their time.
PPLI economics improve materially with scale and negotiated access. That is why the same structure can look expensive at one size and reasonable at another, and why a published range is a starting point rather than a quote.
Fee Drag Against Tax Drag: The Comparison That Decides It
A PPLI wrapper's cost only means something against the tax it is meant to displace, and that comparison depends entirely on what you intend to hold inside it.
Take the unfavorable case first. An investor in the top federal bracket pays 37 percent on ordinary income, plus the 3.8 percent net investment income tax, and a high-tax state can add more than ten points on top. Ordinary income can therefore be taxed above 50 percent at the margin. Private credit and multi-strategy hedge funds distribute mostly ordinary income and realize it continuously, so a taxable holder pays that rate year after year on returns they have not withdrawn.
Now the favorable case. A low-turnover index fund throws off a dividend yield of roughly 1 percent, most of it qualified and taxed at preferential rates, and defers everything else until the holder chooses to sell. There is very little annual tax to remove.
The wrapper costs the same in both cases. What changes is what it buys. Against a sleeve taxed above 50 percent on income the holder never sees, the arithmetic is straightforward. Against an index fund it is close to pure cost, which is a better argument for direct indexing on the equity side than for an insurance wrapper. This is the same logic that runs through tax strategy at higher asset levels: the lever is the character of the income, not the size of the account.
Who Should Not Pay These Costs
PPLI is a poor use of money for an index-only investor, for anyone who may need the capital back inside five years, and for anyone who wants to choose the investments.
The index case follows from the section above. There is almost no annual tax drag to eliminate, so the wrapper is buying very little. Which sleeve belongs in which account is the subject of our guide to asset location.
The short-horizon case follows from the one-time charges. They are incurred at funding and recovered only through years of untaxed compounding. Funding over several years and exiting shortly afterwards captures the cost and very little of the benefit.
The control case is structural rather than a matter of preference. The IRS investor control doctrine requires that someone other than the policyholder direct the investments, and section 817(h) separately requires the underlying account to be diversified. A policyholder who picks the positions is not holding insurance for tax purposes, they are holding their own portfolio with a tax benefit attached, and the treatment fails. Anyone who wants to select holdings should not be in this structure.
One more: the treatment described here is a United States one. A policyholder subject to another country's tax regime needs advice specific to it.
This is the part a seller has no reason to write, and it is the cheapest way to decide whether the rest of this page applies to you. The mechanics behind these charges, including the ownership and diversification rules, are set out in our guide to how PPLI works. The estate case is a separate question, covered in our guide to high-net-worth estate planning, and each disqualifier above is worked through in the pros and cons of PPLI.
Long Angle does not provide legal or tax advice. Private placement life insurance is a tax and estate structure whose treatment depends on individual circumstances. Confirm anything here with your own attorney, CPA or tax professional before acting on it.
Final Thoughts
Work the decision in this order. Settle what you intend to hold inside the policy, because that single choice decides whether the wrapper is buying a lot or almost nothing. Then settle your holding period, because the one-time charges only make sense across decades. Only then compare cost structures, and insist on seeing the policy layer separately from the fund layer. A quote that arrives as one blended percentage is not a quote you can evaluate. Running that sequence backwards, starting from a headline cost figure, is how people end up either dismissing a structure that fitted them or buying one that did not.
Frequently Asked Questions
How much does PPLI cost per year?
The Wall Street Journal reported a typical range of 2 to 4 percent annually in August 2026. That figure blends policy-level insurance charges with the management fees on the assets held inside, so it is not comparable to a fund expense ratio.
What is the DAC tax on a life insurance policy?
It is a pass-through of the deferred acquisition cost an insurer must capitalise under section 848 of the tax code. On a private placement policy it is charged at funding, at roughly 1 percent of premium.
Why are PPLI policies owned through Alaska or South Dakota LLCs?
State premium tax follows the policy's domicile rather than the insured's residence. Both states tax premium on a graduated basis, so the effective rate on a large premium is far below the roughly 2 percent most states charge on the whole amount.
Does PPLI cost more as you get older?
Not straightforwardly. The cost of insurance rate rises with age, but the death benefit the policy must carry falls, and the charge applies only to the gap between death benefit and cash value.
Is there a minimum investment for PPLI in 2026?
No legal minimum exists. Around $5 million of premium is the commonly quoted market floor, set by fixed costs rather than by rule. Economics improve materially with scale and negotiated access.
Is PPLI worth the cost for an index fund investor?
Generally no. A low-turnover index fund is already tax-efficient, yielding roughly 1 percent in mostly qualified dividends and deferring gains until sale. There is little annual tax drag for the wrapper to remove.
PPLI's negotiable costs move with scale, which few individual buyers have.
Long Angle pools the community's demand and negotiates as a single counterparty, so members can evaluate a PPLI offering built on collective scale. Reviewing it carries no expectation to participate.
More From Long Angle
Beyond Wealth Newsletter
Navigating Wealth Podcast
Research & Studies
Alternative Investment Education
Blog