Published
A Guide to High-Net-Worth Estate Planning
A Guide to High-Net-Worth Estate Planning
Master high-net-worth estate planning and safeguard your legacy. Get actionable tips and strategies that protect your assets for generations.
High-net-worth estate planning is the work of deciding how assets are owned, taxed and transferred, and at larger balance sheets ownership matters more than the will. The tools are trusts, lifetime gifting, life insurance held outside the estate, and business succession, each chosen for a specific tax or control problem rather than assembled as a package. The constraint most families underestimate is coordination: an estate attorney, a CPA and an investment manager working from different assumptions can undo the plan each of them drafted correctly.
Key Takeaways
- Ownership, not the will, determines estate tax treatment. An asset you still control at death is in your taxable estate regardless of who inherits it.
- Trusts are chosen for specific jobs. A revocable trust avoids probate but saves no estate tax; an irrevocable trust removes assets from the estate but gives up control.
- Life insurance owned personally is counted in the estate. The same policy owned by an irrevocable trust passes outside it.
- Lifetime gifting trades one tax for another. Gifted assets carry over their basis, so giving away an appreciated position swaps estate tax for capital gains tax.
- Coordination failure is the common defect. Most plans are undone by advisors working from different assumptions, not by a badly drafted document.
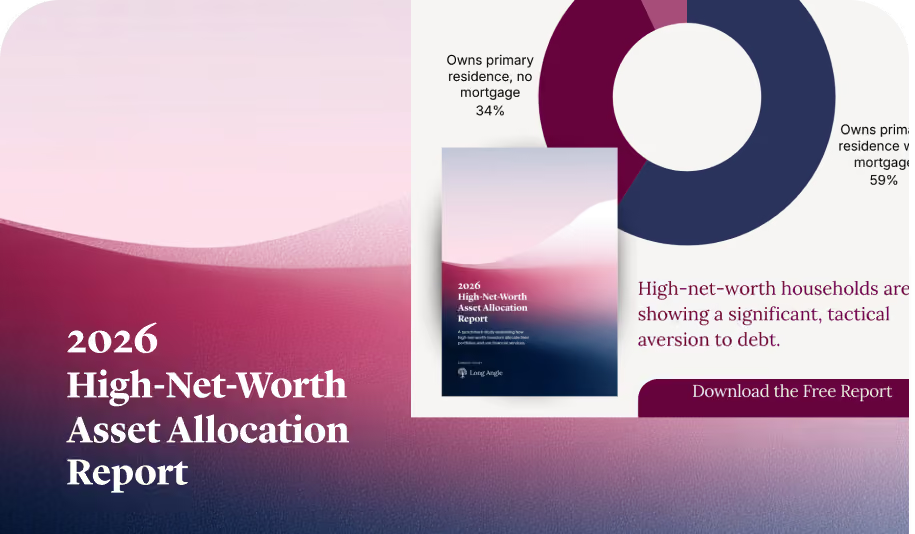
2026 High-Net-Worth Asset Allocation Report
See how high-net-worth investors with an average net worth of $17M are allocating across public equities, private markets, real estate, bonds and cash. Based on benchmark data from 230+ respondents.
What is Estate Planning?
Wealth and estate planning is the process of arranging the management of your estate during your life and after it. For HNW individuals, this includes complex issues like trusts, tax planning, charitable giving, and more.
Effective estate planning strategies aim to minimize taxes, avoid probate, and transfer assets as intended. This process secures your legacy while reducing legal hurdles and financial burdens on loved ones.
Who Needs Estate Planning?
Estate planning is essential for everyone, but it's particularly crucial for HNW individuals since the complexity of protecting and distributing your wealth increases significantly with net worth.
Without a comprehensive estate plan, you could expose your estate to probate, ignite disputes, and erode your assets through taxation. Proper estate planning ensures that accrued wealth is meticulously managed and transferred according to your wishes, protecting your legacy and securing your family’s financial well-being.
Consider seeking counsel on estate planning with Long Angle’s vetted community of HNW individuals who meet regularly online and in-person.
What is Considered a High-Net-Worth Estate?
A high-net-worth estate is one with investable assets over $1 million, excluding the primary residence. Exceeding this financial threshold meant greater complexity in estate planning, encompassing wealth preservation, tax strategies, and asset transfers.
If you have assets beyond your primary residence exceeding $30 million, you’re in the ultra-high-net-worth (UHNW) class. Ultra-high-net-worth estate planning usually involves more intricate strategies due to the scale and complexity of the assets. Issues such as international tax planning, multi-generational wealth transfer, and philanthropic legacies become more pronounced.
Regardless of where your net worth hovers, you and your advisers need to huddle, do the math, and do the long-term planning. The first step is to take stock of your estate.
Don’t neglect the benefits of consulting with HNW peers, who may have invaluable insights to share. Discuss these sensitive topics confidentially in small peer advisory groups.
Why is Estate Planning Important?
Estate planning safeguards your legacy. It's not just about distributing wealth but ensuring that your assets benefit the people and causes you care about in the best possible way and with the most advantageous timing and conditions.
The advantages are clear:
- Asset Distribution: Dictate exactly how and to whom your assets are distributed, avoiding potential disputes among beneficiaries.
- Tax Minimization: Reduce the tax burden on your estate, maximizing the net value passed on to your heirs.
- Legacy Protection: Pass on your values through philanthropic efforts or trusts structured to promote family values.
- Privacy and Security: Ensure that your financial affairs and those of your family remain private and secure.
- Peace of Mind: Feel confident that your wealth is protected and available to support your loved ones according to your wishes.
Types of Trusts for Estate Planning
Trusts are versatile tools in estate planning, offering flexible options for wealth management and legacy preservation.
Here are the main types of trusts:
1. Revocable
Revocable trusts, often used to avoid probate, can be altered or dissolved by a living grantor, providing more flexibility and control over assets.
2. Irrevocable
Once established, irrevocable trusts cannot be easily changed, thereby protecting assets and reducing taxes.
3. Charitable
These allow for philanthropic contributions while providing tax benefits to the grantor. They can be structured to offer income to the grantor before assets pass to the charity.
4. Special Needs
Designed to benefit loved ones with disabilities, these trusts ensure beneficiaries receive financial support without affecting their eligibility for government assistance.
5. “Spendthrift”
Protects the trust’s assets from being squandered by beneficiaries or pursued by their creditors by controlling the distribution of assets.
Understanding the different types of trusts and their specific uses is crucial in estate planning. It allows for tailored strategies that align with individual goals and family needs.
Estate Planning Costs
While estate planning expenses vary based on the complexity of your estate and the strategies you use, understanding the costs involved can help in planning:
- Attorney Fees: These fees are substantial, but they can vary significantly. Complex estates requiring custom trust documents or tailored tax planning strategies incur higher costs.
- Filing and Court Fees: Establishing trusts or executing a will through probate involves various fees, which can add up.
- Financial Advisor Fees: Advisors can help ensure that your plan aligns with your overall financial goals.
- Tax Preparation Fees: Estate planning often involves intricate tax considerations.
4 Essential High-Net-Worth Estate Planning Strategies
Estate planning strategies for high-net-worth individuals typically involve the following:
1. Comprehensive Will and Trust Structure
A robust will and carefully structured trusts form the foundation of any estate plan and dictate asset distribution.
2. Tax Planning
Strategies such as gifting and charitable donations minimize estate taxes, ensuring that a larger portion of your estate benefits your heirs, not just Uncle Sam.
3. Life Insurance
A well-considered policy can provide liquidity for estate taxes and debts, protecting the estate’s value.
4. Succession Planning
If you own a business, you should plan who takes over in your absence to ensure continuity and preserve value.
Implementing these strategies with the help of experienced estate planning professionals can ensure that accumulated wealth is preserved, protected, and passed on as you intend.
Where Private Placement Life Insurance Fits in an Estate Plan
Private placement life insurance combines two effects that most estate structures deliver only one of: investment growth that is not taxed annually, and proceeds that pass to beneficiaries outside the taxable estate.
The first comes from section 7702, which lets income and gains inside a qualifying policy compound without annual tax. The second comes from ownership. If the insured holds the policy personally, section 2042 pulls the death benefit into the taxable estate even though it remains free of income tax under section 101(a). An irrevocable trust owning the policy keeps it outside. Our guide to how PPLI works covers the ownership question and the trust structures in full.
The limit is worth stating plainly, because it is where the structure gets oversold. The growth is deferred, not forgiven. A policyholder who surrenders the contract during life pays ordinary income tax on the gain, so the treatment becomes permanent only through the death benefit. That makes this an estate structure first and a lifetime-access structure second, which is why fit matters more than features. The charges that have to be earned back first are itemised in what a PPLI policy costs.
High-Net-Worth Estate Planning Tips
Here are some insider tips to enhance the effectiveness of HNW estate planning efforts:
- Start Early: Don’t wait for a life-changing event to begin estate planning.
- Take a Team Approach: Estate planning is multifaceted. Engage a team of professionals, including estate attorneys, financial advisors, and tax experts. Make sure they work together well.
- Clarify Your Goals: Whether it’s preserving wealth for future generations, supporting charitable causes, or ensuring the continuity of a family business, clear goals guide wise choices.
- Think Global: If you have assets in other countries, hire an expert to consider the international implications of your estate plan, including foreign taxes and inheritance laws.
- Protect Your Privacy: Explore strategies to keep family matters private, such as using trusts to avoid public probate.
- Educate Your Heirs: Talk with heirs about your plans to prevent confusion and disputes.
- Review Regularly: Estate plans should evolve with life circumstances. Regular reviews are essential to reflect changes in your family, finances, and the legal landscape.
Where Can I Learn More About High-Net-Worth Estate Planning?
Estate planning is a long project rather than a single document. Members bring these questions to the Long Angle community directly: how to structure a trust protector, whether to gift an appreciated position or hold it for the basis step-up at death, and how to get an estate attorney and a CPA working from the same assumptions. A good starting point on the investment side is the Asset Allocation Report, and our guide to asset location covers where each holding belongs once the ownership questions are settled.
Final Thoughts
Estate planning at this level is less about documents than about decisions: who owns what, when it transfers, and which tax it triggers. The documents follow. The most common failure is not a badly drafted trust but a plan assembled by advisors who never spoke to each other, which is why comparing notes with people who have already made these decisions is worth as much as another opinion from someone who bills for one.
Frequently Asked Questions
Is Estate Planning Tax-Deductible?
While you can’t write off estate planning itself, aspects of your plan, like charitable contributions and trusts, can provide tax benefits.
What is Unified Estate Planning?
Unified estate planning considers all aspects of an estate, including trusts, wills, tax planning, and more.
How Often Should HNW Individuals Update Their Estate Plan?
Review your plan every three to five years or immediately after significant life events, such as marriage, divorce, or the birth of a child. Make sure to monitor changes in tax law as well.
Is Estate Planning the Same as a Will?
No. A will is crucial, but it’s just one aspect of estate planning.
What are the Other Components of Estate Planning?
Beyond wills, estate planning includes trusts, healthcare directives, powers of attorney, beneficiary designations, tax strategies, and business succession. Each of these is a research topic that you and your advisors should pursue and discuss as needed.
Most estate plans fail on coordination, not on drafting.
Long Angle members work through trust structures, basis tradeoffs and advisor coordination with peers who have already made those calls. Vetted, candid, and no one in the conversation is selling anything.
More From Long Angle
Beyond Wealth Newsletter
Navigating Wealth Podcast
Research & Studies
Alternative Investment Education
Blog