Written by Scott Nixon
Questions to Ask an Estate Planning Attorney, and What It Costs
Questions to Ask an Estate Planning Attorney, and What It Costs
What to ask an estate planning attorney at a first meeting, what to bring, and what estate plans and trusts cost high-net-worth households to run.
Scott Nixon
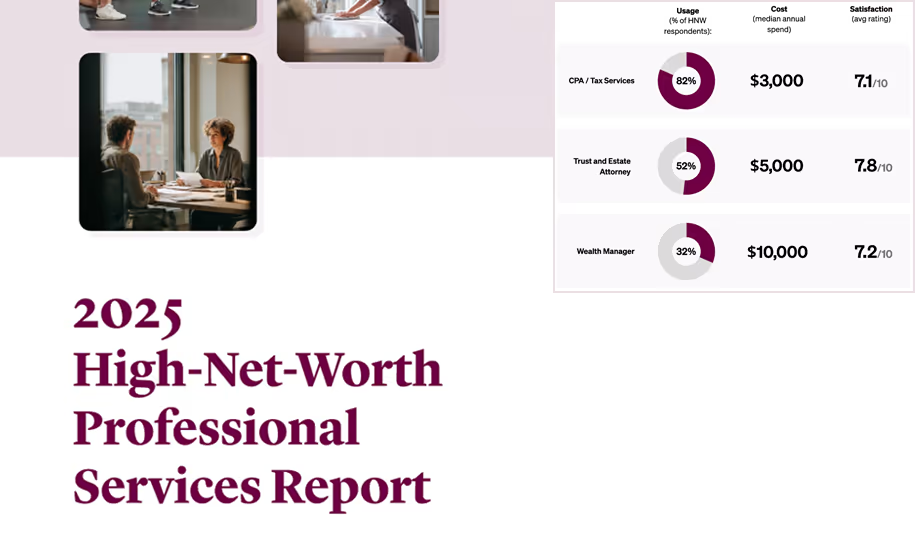
Ask an estate planning attorney what the plan should do for your family, whether you need irrevocable trusts or only a will and revocable trust, who should serve as trustee, how the fee is set and what it covers, and when the plan will be reviewed. At net worth above $2.2M, median household spending on a trust and estate attorney was $5,000 a year, and use rose from 44% of households under $5M to 69% at $25M and up, in Long Angle's 2025 Professional Services Report (114 member respondents). The sample is small and self-selected, so treat it as directional.
Key Takeaways
- Ask about goals, trust type, trustees, the fee and the review schedule; bring a balance sheet showing how each asset is titled.
- A will and revocable trust avoid probate but not estate tax; irrevocable trusts can reduce estate tax at the cost of control.
- In Long Angle's 2025 study of 114 members, median spending on a trust and estate attorney was $5,000 a year, and 57% of clients paid a project fee.
- A revocable trust is usually priced with the basic plan; an irrevocable trust adds drafting, funding, a gift tax return and costs that continue after setup.
- In the 2026 study of 233 members, 82% have an estate plan, and 73% of those with one are not updating it.
2025 High-Net-Worth Professional Services Study
See what HNW households with an average net worth of $5M+ spend on advisors, estate planning, tax, and professional services — benchmarked across 200+ respondents.
What to Ask an Estate Planning Attorney: The Short List
A first meeting with an estate attorney goes best when you arrive with clear goals and a list of what you own, and leave with a written scope and fee. The questions below cover the plan, the people in it, the fee and the upkeep. None of them is a test of the attorney; each one tells you what you are buying.
| Question to ask | Why it matters |
|---|---|
| What should this plan do for my family, in plain terms? | Sets the goals first, so the documents follow from them rather than from a standard package |
| Do I need only a will and revocable trust, or irrevocable trusts as well, and why? | Separates the foundation every plan needs from structures that save estate tax but give up control |
| Who should serve as trustee and executor, and who backs them up? | The people running the plan matter as much as the documents |
| How will my children or other heirs receive assets, and at what ages? | Distribution terms are where most family disagreements start |
| Is the fee flat or hourly, and what exactly does it include? | Funding the trust, retitling accounts and later revisions are often priced separately |
| Who funds the trust and updates beneficiary designations? | An unfunded trust does little; designations on retirement accounts and insurance override the will |
| How will you work with my CPA and financial advisor? | Tax, investment and estate decisions affect each other |
| When should we review the plan, and what does a review cost? | Plans drift as families, assets and tax law change |
Source: Long Angle editorial checklist. General education, not legal advice.
If the attorney's answers are specific to your family and the fee is in writing, the meeting did its job. This page is general education, not legal advice, and an attorney licensed in your state is the right source for what applies to you.
What to Bring to the First Meeting
Most of what makes a first meeting productive happens before it. Attorneys spend early sessions gathering facts, and every fact you bring is time you are not billed for and a better question you can ask. A one-page summary usually covers it:
- A balance sheet listing each asset, its approximate value and how it is titled: in your name, jointly, in a trust or in an entity.
- Beneficiary designations on retirement accounts, life insurance and transfer-on-death accounts, since these pass outside the will.
- Existing documents, including any prior will, trust, prenuptial agreement, operating agreements and buy-sell agreements.
- Private holdings such as company equity, fund interests and real estate partnerships, with any transfer restrictions.
- Family facts: children and their ages, any beneficiary with special needs, and states or countries where family members live.
- Your goals, in a sentence or two each: who you want to provide for, when, and what you want to avoid.
Arriving with this also changes the conversation. Instead of asking what a revocable trust is, you can ask whether your company shares can go into one and what that does to any transfer restrictions.
Questions About the Plan Itself
The core decision is how far beyond the basics to go. A basic plan usually means a will, a revocable living trust, powers of attorney and a healthcare directive. A revocable trust avoids probate and keeps the estate private, but it does not reduce estate tax because you still control the assets. Irrevocable trusts, such as spousal lifetime access trusts (SLATs) and grantor retained annuity trusts (GRATs), can move future growth out of the taxable estate, at the cost of control and flexibility.
Useful questions at this stage:
- Does my estate's size and trajectory justify any irrevocable trust now, or should we revisit in a few years?
- If you recommend an irrevocable trust, how much access and control do I keep, and what happens if circumstances change?
- How does this plan hold up if the federal exemption or my state's estate tax changes?
- If I expect a liquidity event, what needs to be in place before it, and what becomes harder after?
- Who can change the trust's terms later, and through what process?
The federal estate and gift tax exemption rose to $15 million per person from January 2026 under the One Big Beautiful Bill Act, which changes the urgency for many households below that level. Long Angle's guide on when to start estate planning covers timing and sequencing, and the high-net-worth estate planning guide explains how each type of trust works. How much to leave children, and on what schedule, is covered in setting up a trust fund for kids.
Questions About Fees and Scope
Estate attorneys price work in two main ways. In Long Angle's 2025 Professional Services Report (114 member respondents), 57% of clients were billed on a project basis and nearly a third paid hourly. A project fee makes the cost of setup predictable; hourly billing can suit open-ended work such as a business succession plan or ongoing trust administration.
Either way, the scope decides the real cost. Ask the attorney to confirm in writing:
- Which documents are included, and how many rounds of revisions.
- Whether funding the trust is included: retitling accounts, recording deeds, assigning entity interests.
- Whether the fee covers coordination with your CPA and advisor, and any gift tax returns the plan requires.
- What a later amendment or a periodic review costs, and whether there is an ongoing retainer.
- Who on the firm's team will do the drafting and who you will speak with.
Satisfaction with estate attorneys is relatively high among Long Angle members: they rated trust and estate attorneys 7.8 out of 10 in the 2025 report, the highest of the three financial services measured, ahead of wealth managers at 7.2 and CPAs at 7.1. Clear scope at the outset is part of how that relationship starts well.
How Much Estate Planning Costs
At net worth above $2.2M, median household spending on trust and estate attorney services was $5,000 a year in Long Angle's 2025 Professional Services Report (114 member respondents). The report notes that costs vary by region. That figure is annualized spending on the attorney relationship, not a quote for drafting a plan, so ask any attorney you meet to price the initial plan and the annual upkeep as two separate numbers.
What moves the setup price is scope more than the attorney's rate. A basic plan, meaning a will, a revocable living trust, powers of attorney and a healthcare directive, is a defined package that many firms quote as a project. Each irrevocable trust adds drafting, funding work and often a gift tax return, and holdings that are hard to value, such as private company shares or fund interests, can add an appraisal. Ongoing cost depends on how often the plan is reviewed, whether a professional trustee is paid, and how much administration the trusts need each year.
Keeping the plan current is the part most households skip. In Long Angle's 2026 Asset Allocation Report (233 respondents, average net worth about $17M), 73% of those with an estate plan were not updating it, including 31% who knew they needed to. Asking what a review costs at the first meeting makes that step easier to schedule later.
How Much a Trust Costs to Set Up and Maintain
For a household working with an estate attorney, the cost of a trust depends on which kind it is and what it will hold. A revocable living trust is normally drafted as part of the basic plan and priced with it. An irrevocable trust is a separate piece of work with costs that continue after it is signed. The table sets out where the money goes.
| Trust | What you pay for at setup | What continues after setup |
|---|---|---|
| Revocable living trust | Drafting, usually inside the basic plan package; funding it by retitling accounts and recording deeds | Little while you are alive; amendments when family or assets change |
| Irrevocable trust (such as a SLAT, GRAT or dynasty trust) | Separate drafting; funding; a gift tax return reporting the transfer | Trustee time or fees; annual administration; a trust income tax return if it is not a grantor trust |
| Trust holding private company shares or fund interests | An appraisal to support the value reported; a review of transfer restrictions in the governing documents | Updated valuations when further gifts are made; coordination with the company or fund |
Source: Long Angle editorial summary. General education, not legal or tax advice. Ask your attorney and CPA to price each item for your plan.
Irrevocable trusts are a minority choice even in this population. In the 2026 Asset Allocation Report, 24% of respondents had an advanced plan with irrevocable trusts or similar structures, and 58% had a basic plan. The useful question for an attorney is not what a trust costs in general but what this trust will save or protect against what it costs to create and run, and how much access and control it leaves you.
Tax questions that sit alongside a trust, such as gift tax returns and the basis of gifted assets, are worth raising with your CPA as well. Long Angle's guide to high-net-worth accountants covers that side, and how transfer taxes work in estate planning explains the gift and estate tax mechanics.
How Many High-Net-Worth Households Use an Estate Attorney
Just over half of respondents to the 2025 Professional Services Report, 52%, used a trust and estate attorney, and use rose with wealth:
| Net worth | Uses a trust and estate attorney |
|---|---|
| Under $5M | 44% |
| $5M to $10M | 43% |
| $10M to $25M | 57% |
| $25M and up | 69% |
Source: Long Angle 2025 High-Net-Worth Professional Services Report, 114 respondents, all with net worth above $2.2M, fielded August to September 2025. Respondents are Long Angle members who chose to take part, not a representative sample of high-net-worth households. The report does not state the size of each band, so read these as directional.
The report found that age was not the deciding factor; complexity of assets was. If you already have documents, a first meeting about a new trust is a good moment to ask what else in the existing plan is out of date. The maintenance gap is covered in why most high-net-worth estate plans need updating, and the full usage, cost and satisfaction data is in the 2025 High-Net-Worth Professional Services Report.
After the Meeting: Comparing Proposals
If you meet more than one attorney, compare proposals on the same terms: the documents included, the fee and how it is set, who does the work, how funding is handled and the review schedule. A higher fee that includes funding and coordination can cost less in total than a lower one that does not. Ask peers who have been through the same process which questions they wish they had asked; that is often where the most useful answers come from.
Final Thoughts
The questions that make a first estate planning meeting productive are about your family, not about legal vocabulary: what the plan should do, how much control you keep, who runs it, what it costs and when it gets reviewed. Bring a clear picture of what you own and how it is titled, and ask for the setup fee and the annual upkeep in writing as two numbers. Judge a trust by what it does over the years it runs, not by the drafting fee alone. Treat this as general education and take the specifics to an attorney licensed in your state.
Frequently Asked Questions
What questions should I ask an estate planning attorney?
Ask what the plan should accomplish for your family, whether you need irrevocable trusts or only a will and revocable trust, who should serve as trustee, how heirs will receive assets, whether the fee is flat or hourly and what it includes, who funds the trust, and how often the plan should be reviewed.
How much does estate planning cost?
At net worth above $2.2M, median household spending on a trust and estate attorney was $5,000 a year in Long Angle's 2025 Professional Services Report (114 member respondents). Plans with irrevocable trusts cost more to set up and maintain. The sample is small and self-selected, so treat it as directional.
How much does a trust cost?
A revocable living trust is usually priced inside the basic plan. An irrevocable trust costs more: separate drafting, funding, a gift tax return, often an appraisal, and trustee and tax filing costs every year after. Ask for setup and annual costs in writing.
Do estate planning attorneys charge a flat fee or by the hour?
Both are common. In Long Angle's 2025 Professional Services Report (114 member respondents), 57% of clients were billed on a project basis and nearly a third paid hourly. Ask what a project fee includes, especially trust funding and later revisions.
What should I bring to my first meeting with an estate attorney?
A one-page balance sheet showing each asset and how it is titled, current beneficiary designations, any existing wills, trusts or prenuptial agreements, details of private company or fund holdings, basic family facts, and a short statement of your goals.
How often should an estate plan be updated?
After major life events, large changes in net worth and changes in tax law. In Long Angle's 2026 Asset Allocation Report (233 member respondents), 73% of those with a plan were not updating it, including 31% who knew they needed to.
An estate plan is easier to shape with peers who have built one.
Trusted Circles put six to eight Long Angle members at a comparable wealth stage in a moderated room for three hours a month over Zoom. Long Angle membership is free; Trusted Circles is a separate paid program.
More From Long Angle
Beyond Wealth Newsletter
Navigating Wealth Podcast
Research & Studies
Alternative Investment Education
Blog