Written by Scott Nixon
At What Net Worth Do You Need a Trust? What Members at $5 Million Do
At What Net Worth Do You Need a Trust? What Members at $5 Million Do
Members at $5M to $10M used an estate attorney at the same rate as those under $5M. Use rose to 69% above $25M. What a will covers and where a trust fits.
Scott Nixon
No law sets a net worth at which you need a trust. At $5 million to $10 million, 43% of Long Angle members surveyed used a trust and estate attorney, the same rate as those under $5 million (44%); use rose to 57% at $10 million to $25 million and 69% above $25 million (2025 Professional Services Report, 114 respondents, August-September 2025). In a separate study of 233 respondents, 82% had an estate plan and 24% held an advanced structure such as an irrevocable trust. The 2026 federal estate tax exemption is $15 million per person.
Key Takeaways
- At $5 million to $10 million, 43% of members surveyed used a trust and estate attorney, the same as under $5 million (44%); use rose to 57% at $10 million to $25 million and 69% above $25 million.
- 82% of members surveyed had an estate plan: 58% basic (will, medical directive, revocable trust), 24% an advanced structure such as an irrevocable trust and 18% none.
- No law sets a net worth at which a trust is required, and the 2026 federal estate tax exemption is $15 million per person.
- Below the exemption, a revocable trust is used mainly to avoid probate, keep the estate private and plan for incapacity, and it does not reduce estate tax.
- 73% of members with a plan were not updating it, and 31% said they knew it needed updating.
2025 High-Net-Worth Professional Services Study
See what HNW households with an average net worth of $5M+ spend on advisors, estate planning, tax, and professional services — benchmarked across 200+ respondents.
You Have $5 Million and a Will. Is a Will Enough?
Most respondents at this level have some plan, and a quarter have gone past the basics. In Long Angle's 2026 Asset Allocation Report, 82% of respondents had an estate plan: 58% a basic plan and 24% an advanced structure such as an irrevocable trust.
| Estate plan in place | Share of respondents |
|---|---|
| Basic (will, medical directive, revocable trust) | 58% |
| Advanced (irrevocable trust and similar structures) | 24% |
| None | 18% |
Source: Long Angle 2026 High-Net-Worth Asset Allocation Report, 233 respondents, average net worth about $17M, fielded December 2025-January 2026. The basic category does not separate a will from a revocable trust.
The sample sits close to the $5 million question. 85% of respondents reported more than $5 million in net worth, and 48% fell between $2 million and $10 million. The full finding, including how few of these plans are current, is in how often high-net-worth investors update their estate plans.
The basic category bundles a will, a medical directive and a revocable trust into one answer. That means the data cannot say how many respondents hold a revocable trust and how many rely on a will alone. What it does show is that a will with a medical directive is where most plans at this level stop, and that the advanced share is a minority even in a sample whose average net worth is about $17 million.
A will names who receives your assets and who serves as executor and guardian. It takes effect at death and generally passes through probate, the court process that validates the will and supervises distribution. A funded revocable trust holds assets during your lifetime and lets a successor trustee take over without probate. Whether that matters at $5 million depends on where your assets sit and which state's law applies, which is a question for an estate attorney.
Who Needs a Trust: What Members at Each Wealth Level Do
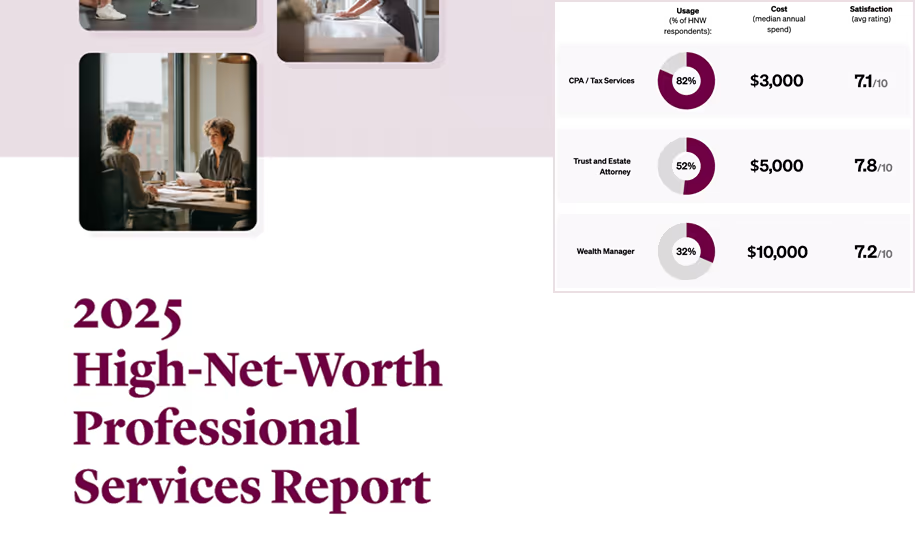
Use of a trust and estate attorney is flat below $10 million and rises above it. In Long Angle's 2025 Professional Services Report, 43% of respondents with $5 million to $10 million used one, against 44% of those under $5 million, 57% at $10 million to $25 million and 69% above $25 million.
| Net worth | Used a trust and estate attorney |
|---|---|
| Under $5M | 44% |
| $5M to $10M | 43% |
| $10M to $25M | 57% |
| $25M+ | 69% |
| All respondents | 52% |
Source: Long Angle 2025 High-Net-Worth Professional Services Report, 114 respondents, all with net worth over $2.2M, fielded August-September 2025. Band sizes are not reported, so read the differences as directional.
Attorney use is a proxy for professional estate work, and it tells you who paid for a plan to be drafted. It does not say which documents that plan contains. Read that way, respondents at $5 million to $10 million look much like those below $5 million, and the step up comes at $10 million.
The report found that age is not a determining factor in who uses an estate attorney. It points instead to the complexity of assets, such as private investments, multiple properties and family businesses, as the driver behind whether people seek out trust and estate services. Two people at $6 million can sit on opposite sides of that line: one with a brokerage account and a home, the other with a stake in a private company and rental property in a second state.
Once you decide to hire one, the questions to ask an estate attorney cover how to screen a firm. The full study, with satisfaction and use across other professional services, is in the 2025 High-Net-Worth Professional Services Report.
When Do You Need a Trust Below the Estate Tax Exemption?
At $5 million, an estate sits well below the federal estate tax exemption. The IRS lists the 2026 basic exclusion amount, the federal estate and gift tax exemption, as $15 million per person, and the annual gift exclusion as $19,000 per recipient.
Below that line, a revocable trust is generally used for practical purposes. Assets titled to a funded trust can pass without probate, which can save time and keep the inventory of an estate out of the public court record. A successor trustee can manage trust assets if you become unable to, without a court-appointed conservator. And a trust can set terms for when and how beneficiaries receive money, which a simple will does not do as easily.
A revocable trust does not reduce federal estate tax. Assets in it remain part of your taxable estate, because you keep control of them. It also has to be funded: a trust that holds nothing leaves the assets to pass under the will. State rules on probate, and in some states on estate tax, differ from the federal picture. This page describes what members reported and how these documents generally work; it is not legal advice.
The sequence that most planning guidance follows is foundation first: a will, powers of attorney, a medical directive and beneficiary designations that match the plan. When to start estate planning covers that order and the conditions under which more advanced structures come in.
Do You Need an Irrevocable Trust at $5 Million?
About a quarter of respondents hold one or a similar structure. 24% of respondents to the 2026 Asset Allocation Report reported an advanced estate plan, a category the report describes as often involving irrevocable trusts, along with family limited partnerships and charitable trusts.
The report describes irrevocable trusts as structures that provide more protection from creditors and reduce future estate tax liabilities. That second use is tied to the exemption. With the 2026 federal exemption at $15 million per person, an estate of $5 million sits well under it today. Our timing page sets out the conditions under which advanced structures come into play: an estate on course to exceed the exemption, appreciating assets that benefit from early transfer, and comfort with the access restrictions that come with an irrevocable structure.
Moving assets into an irrevocable trust generally means giving up control of them, and the decision is hard to reverse. How GRATs, SLATs and IDGTs fit those conditions is covered in when to start estate planning, and the main trust types are compared in high-net-worth estate planning. Where children are the beneficiaries, the age and terms of distribution become the harder question, which is covered in trust funds for kids.
You Set Up the Plan Years Ago and Have Not Looked Since
Most plans are out of date by their owners' own account. Among respondents with an estate plan, 73% were not updating it, and 31% said they knew it needed updating.
| Estate plan status | Share of respondents with a plan |
|---|---|
| Not updating | 42% |
| Not updating, but know I need to | 31% |
| Currently updating documents | 28% |
Source: Long Angle 2026 High-Net-Worth Asset Allocation Report, 233 respondents, average net worth about $17M, fielded December 2025-January 2026. Respondents with an estate plan. Totals 101% due to rounding.
The report names the triggers for a review: marriage, divorce, the birth of a child, significant tax and legal changes, and major changes in net worth or property. For someone who drafted a will at $1 million and now holds $5 million, the last of those has already happened. Beneficiary designations on retirement accounts and life insurance pass outside a will and a trust, so they are worth checking against the plan at the same time.
The change in the federal exemption to $15 million for 2026 is the kind of legal shift the report has in mind. A plan drafted around an older figure may use formulas that now work differently, and an estate attorney can say whether yours does. The full allocation data behind these figures is in the 2026 High-Net-Worth Asset Allocation Report.
How to Read These Numbers
Both studies survey Long Angle members, who answer voluntarily and are not a representative sample of wealthy Americans. The attorney figures come from 114 respondents split across four net worth bands, with band sizes not reported, so a one-point gap between the two lowest bands carries no weight. The estate plan figures come from 233 respondents and are not cut by net worth, so no figure here says what share of people at exactly $5 million hold a trust.
What the two studies support together is narrower and still useful. Respondents at $5 million to $10 million used estate attorneys at the same rate as those below $5 million, most respondents across the sample had a plan, and most of those plans were basic and not being updated. Members at this level compare notes on which structure they chose, what it cost to keep current and whether they would set it up the same way again. Long Angle is a free community for people with more than $3 million in investable assets, excluding a primary residence, and every member's assets are verified.
Final Thoughts
The data puts the step up in professional estate work at $10 million: respondents at $5 million to $10 million used estate attorneys at the same rate as those below $5 million. Most respondents had a plan, a quarter held an advanced structure, and most plans were not being kept current. Whether a trust fits at $5 million turns on how your assets are held, where you live and who inherits, and members at this level compare notes on what they chose and why before they sit down with an estate attorney.
Frequently Asked Questions
Do I need a trust if I have a will?
A will generally passes assets through probate, while assets in a funded revocable trust can pass without it; neither reduces federal estate tax. In Long Angle's 2026 Asset Allocation Report, 58% of respondents had a basic plan of a will, medical directive or revocable trust. State law varies, and this is not legal advice; an estate attorney can say which fits your situation.
At what net worth do you need an irrevocable trust?
No legal threshold exists. The IRS sets the 2026 federal estate tax exemption at $15 million per person, and 24% of respondents to Long Angle's 2026 Asset Allocation Report held an advanced structure such as an irrevocable trust. Whether one fits below the exemption depends on expected growth, appreciating assets and how much access you need, which is a question for an estate attorney.
How many people with $5 million or more have a trust?
Our data shows 24% of respondents with an advanced structure such as an irrevocable trust, in a sample where 85% reported more than $5 million in net worth. The 58% with a basic plan includes revocable trusts but does not separate them from wills, so the total share holding any trust is not known.
Do wealthier people use estate attorneys more?
In Long Angle's 2025 Professional Services Report, use was 44% under $5 million, 43% at $5 million to $10 million, 57% at $10 million to $25 million and 69% above $25 million. Band sizes were not reported, so read the pattern as directional. The report found age was not a determining factor.
Want to know how other members set up their estate plans?
Long Angle is a free, vetted community of founders, executives and investors with more than $3 million in investable assets, excluding a primary residence, comparing notes on trusts, taxes and family decisions.
More From Long Angle
Beyond Wealth Newsletter
Navigating Wealth Podcast
Research & Studies
Alternative Investment Education
Blog